Introduction
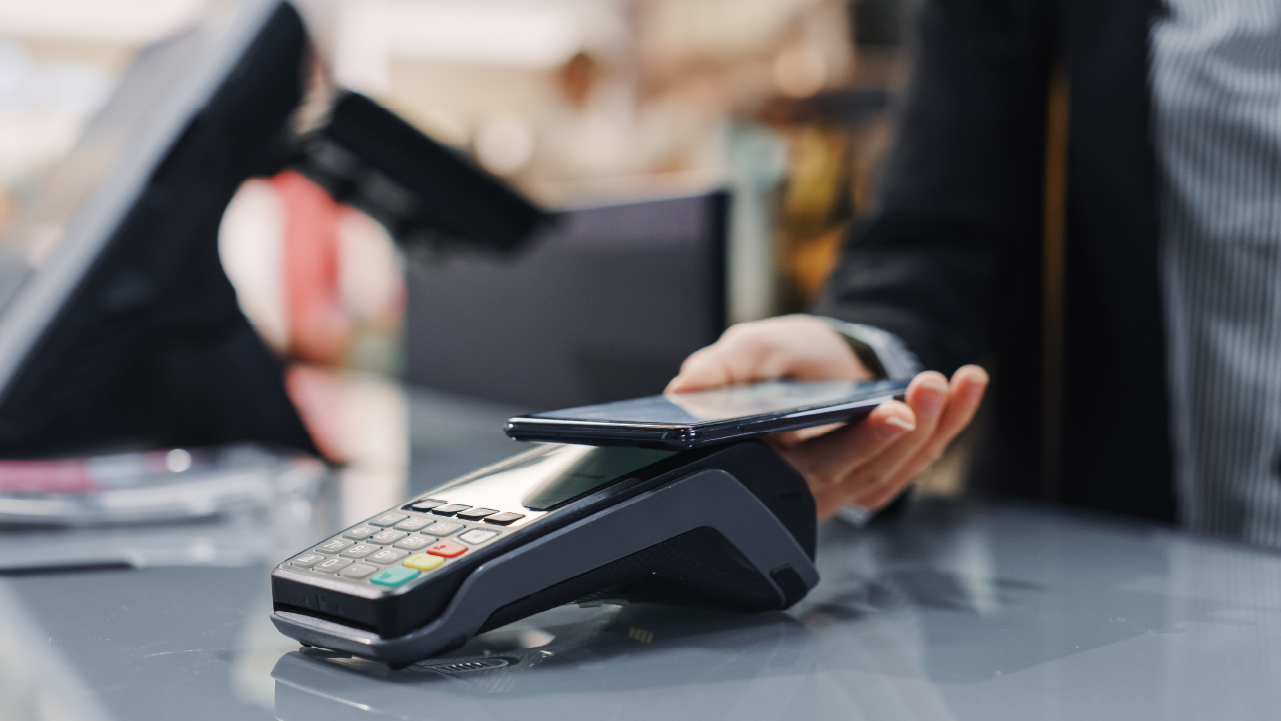
Mobile-based transactions have become a common part of everyday digital life. Consumers can use their smartphones to purchase digital content, make small-value payments, access online services, or obtain mobile gift certificates. As these options have expanded, terms such as mobile payment settlement, settlement rates, and conversion services have also become more widely used.
For consumers considering any type of settlement or conversion service, understanding how the process works is important. A transaction may involve several stages, including payment authorisation, service processing, applicable fees, verification, and final settlement. The amount involved at the beginning of a transaction may therefore differ from the amount ultimately received.
This makes it important to look beyond speed or convenience. Consumers should understand the transaction structure, compare the final amounts involved, review service conditions, and consider security before making a decision. A clear understanding of the process can help reduce unexpected costs and support more responsible financial choices.
What Does Mobile Payment Settlement Mean?
Mobile payment settlement generally refers to the process of calculating and processing the value associated with a mobile-based transaction. In a standard purchase, a consumer pays for a product or service and receives that product or service in return. Settlement services can involve an additional process in which the value of an eligible transaction is calculated and transferred according to specific conditions.
This is different from simply using a smartphone to purchase something. A conventional mobile payment ends when the payment is accepted and the purchased product or service is provided. A settlement process may involve additional calculations, deductions, verification procedures, and payment arrangements.
Several terms may appear when consumers research these services. A gross transaction amount refers to the initial value associated with a transaction, while a settlement amount refers to the amount available after applicable deductions. A settlement rate represents the proportion of the original value that may be returned or processed after relevant costs.
The terminology used by service providers can vary. One provider may describe a service as settlement, while another may use terms related to conversion or transaction processing. Because terminology is not always standardised, consumers should examine the actual terms rather than relying only on the service name.
Understanding the complete transaction structure is particularly important where fees or deductions apply. A service that appears attractive based on its advertised rate may produce a different final amount after all applicable costs have been considered.
How Settlement Rates Affect the Amount a User Receives
Settlement rates are an important consideration because they help determine the difference between the original transaction value and the final amount processed. A higher stated rate does not necessarily mean that it will produce the best outcome if additional charges are applied elsewhere.
For example, if an eligible transaction has a gross value of £100 and a hypothetical settlement rate of 85%, the initial calculation would produce £85 before considering any additional applicable deductions. If another charge of £5 applies, the final amount would be £80. The example demonstrates why consumers should look at the complete calculation rather than focusing on one percentage.
Settlement rates can also vary depending on the type of transaction. Mobile micropayments, digital content charges, and mobile gift certificates may have different processing conditions. Eligibility, transaction limits, verification requirements, and provider policies can also affect the final calculation.
Consumers should therefore ask for the actual amount that will be processed before agreeing to a transaction. A clear explanation should identify the gross amount, applicable rate, deductions, and expected final amount.
It is also important to remember that settlement rates are not necessarily fixed across all situations. They may depend on the transaction type, amount, service conditions, and other eligibility factors. Comparing the complete terms is more useful than comparing advertised percentages alone.
Comparing Settlement Options for Different Transaction Types
Different mobile-based transactions can involve different settlement processes. Understanding these differences can help consumers determine whether a particular service is relevant to their circumstances.
For consumers researching Mobile payment services, Hanaplus365 is an online information and consultation platform providing guidance on mobile payment services, digital content payment methods, and mobile gift certificates. The website provides information about service procedures, important precautions, and customer support to help users make better-informed decisions. Service conditions and availability can differ depending on individual circumstances, eligibility requirements, and mobile carrier policies.
Mobile micropayments are one category that consumers may encounter. These transactions generally involve small-value purchases charged through a mobile carrier or associated payment system. Before considering any settlement-related service, consumers should understand the applicable transaction limits, billing arrangements, and eligibility requirements.
Digital content and information-use charges represent another category. These may relate to digital products, applications, online content, or other services where the payment is processed through a mobile account. The specific rules can differ depending on the platform, merchant, carrier, and type of content involved.
Mobile gift certificates and vouchers are another distinct category. Their value may depend on the issuing platform, type of voucher, redemption conditions, and whether the certificate is eligible for a particular service.
Although these transaction types may all involve mobile devices, they should not automatically be treated as identical. Each can have different procedures, restrictions, fees, and documentation requirements. Consumers should therefore confirm the exact transaction category before proceeding.
Questions to Ask Before Choosing a Settlement Service
A consumer can reduce uncertainty by asking several practical questions before agreeing to a settlement or conversion process. Clear answers can make it easier to compare providers and understand the financial implications.
- What is the exact final settlement amount?
The provider should explain how the original transaction value is converted into the final amount. Consumers should ask whether the quoted amount is gross or net of fees. - Are there additional fees or deductions?
A stated settlement rate may not represent the final amount. Consumers should check for processing fees, service charges, transfer costs, or other deductions. - How long does processing take?
Processing times can vary. It is useful to understand whether the stated timeframe refers to approval, processing, or the actual receipt of funds. - Is identity or transaction verification required?
Some services may require verification before processing. Consumers should understand what information is required and why it is necessary. - What happens if a transaction is cancelled or disputed?
Cancellation and dispute procedures should be clear before a transaction begins. Consumers should understand whether a completed transaction can be reversed and whether additional costs could apply. - Is customer support available if a problem occurs?
Accessible customer support can be important when dealing with payment-related issues. Consumers should know how to contact the provider and what type of assistance is available.
These questions can help distinguish transparent services from those that provide limited information. A provider that clearly explains conditions, costs, procedures, and responsibilities gives consumers a stronger basis for making an informed decision.
Safety Considerations When Using Online Settlement Services
Security should remain a central consideration whenever a financial transaction takes place online. Consumers may encounter websites or individuals promising unusually high returns, immediate processing, or unusually simple procedures. Such claims should be assessed carefully rather than accepted at face value.
Consumers should verify the identity and legitimacy of a service provider before sharing transaction information. The website should provide clear information about its services, terms, support channels, and relevant policies.
Personal information should also be handled carefully. Consumers should avoid sharing unnecessary passwords, authentication codes, security credentials, or other information that could allow another party to access an account. Legitimate transaction procedures should clearly explain what information is required.
Records should be retained throughout the process. Screenshots, transaction confirmations, receipts, communications, and other relevant documentation can be useful if a disagreement or technical problem later occurs.
Consumers should also be cautious of unrealistic promises. A service that focuses heavily on exceptionally high returns while providing little information about fees, eligibility, or risks may warrant additional scrutiny. Taking time to verify the details can be more valuable than prioritising speed.
How to Evaluate Convenience Against Cost and Risk
Convenience can be attractive when dealing with digital payment services, but it should not be the only factor influencing a decision. A fast process may still involve costs, eligibility restrictions, or risks that need to be understood beforehand.
A practical evaluation can include the following considerations:
- Compare the final amount rather than the headline rate.
The most useful figure is the amount remaining after all applicable deductions. Comparing final amounts can provide a more accurate picture of the financial outcome. - Review the complete terms before proceeding.
Conditions relating to eligibility, transaction limits, processing, cancellations, and fees should be understood before a transaction is initiated. - Consider whether the service is genuinely necessary.
Consumers should consider the purpose of the transaction and whether there are simpler or lower-cost alternatives available. - Evaluate transparency as part of the decision.
Clear information about rates, fees, procedures, and support can be an important indicator of a well-structured service. - Protect account and personal information.
Convenience should never require consumers to ignore basic security practices. Sensitive authentication details should remain protected. - Keep financial records.
Maintaining transaction details allows consumers to review what happened and provides useful evidence if a payment issue arises.
A balanced approach therefore considers convenience, cost, transparency, security, and personal circumstances together. This can help prevent a quick decision from creating an unexpected financial obligation later.
Conclusion
Mobile payment settlement can involve more than simply transferring the value of a mobile transaction. Depending on the transaction type, consumers may need to consider settlement rates, fees, eligibility conditions, processing procedures, security requirements, and final amounts.
Understanding these factors before using a settlement or conversion service can help consumers make more informed decisions. Rather than focusing only on speed or an advertised percentage, it is useful to examine the complete transaction structure and confirm the final amount after applicable deductions.
Consumers should also protect personal information, retain transaction records, verify service details, and ask questions whenever terms are unclear. With greater awareness of costs, procedures, and potential risks, mobile-based financial decisions can be approached more carefully and responsibly.